- with Senior Company Executives, HR and Finance and Tax Executives
- with readers working within the Accounting & Consultancy and Business & Consumer Services industries
Download a PDF copy of this Blog here.
Many taxpayers assume that once a CRA auditor starts an Audit, the Audit needs to be completed, with no opportunity to reach an early settlement on contentious issues. To the contrary, CRA has recently confirmed that many Audits can, in fact, be settled – albeit only after being subject to additional internal review before becoming final.
In the Tax Audit Series below, we review the CRA’s Audit Settlement Process, including CRA’s internal approval processes for settlements and the role played by its Audit File Resolution Committee ("AFRC") in significant or precedent-setting cases.
CRA’s Internal Audit Settlement Process
At a recent industry roundtable, CRA confirmed and explained that, as part of its commitment to supporting the efficient resolution of tax disputes and promoting Audit quality, settlement decisions do not always rest with the individual Auditor assigned to the file. Significant matters may require additional review through various internal referral processes involving regional and National Technical Advisors, Headquarters Specialists, the Department of Justice, and, in appropriate cases, the AFRC.
Because these internal referral processes may apply before a Reassessment is issued, a Settlement Proposal discussed with the assigned Auditor may still be rejected where it is inconsistent with CRA’s best interpretation of tax law or raises issues of inconsistency.
Significant Audits and the AFRC
CRA explained that it established the AFRC in 2017 to promote consistency and timely, efficient resolution of files at the Audit Stage. The Committee is composed of senior representatives from the Compliance Programs Branch, the Legislative Policy and Regulatory Affairs Branch, tax services offices and the Department of Justice.
Significant Audits, meeting certain specified criteria, MUST be referred to the AFRC (examples include where they involve significant dollar amounts, unusual transactions, issues that may affect other taxpayers, or matters attracting broader public interest). Since 2019, the Committee has reviewed 42 settlement proposals, approving 19 while rejecting or requiring changes to 23.
Practical Implications for Businesses
For businesses, these comments serve as an important reminder that preliminary settlement discussions with an Auditor should not necessarily be viewed as reflecting the CRA's final position. Significant GST/HST, Excise Tax, and Customs disputes may require additional internal approvals before any settlement can be finalized.
Understanding CRA's internal settlement processes can assist businesses in managing expectations, developing effective settlement strategies and resolving disputes more efficiently.
Takeaways
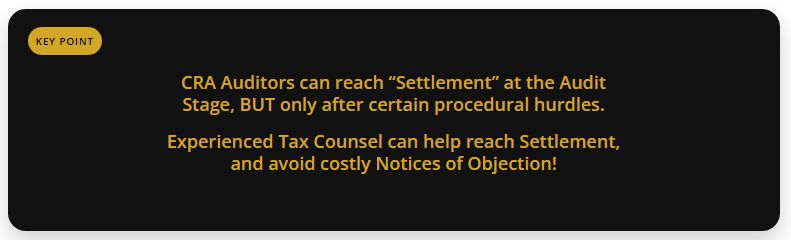
CRA recently confirmed that Audit Settlement exists, and that significant Audit Settlement Proposals will generally require layers of internal review and approval. While taxpayers often negotiate directly with the assigned Auditor, important files may be subject to further review by Headquarters and specialized committees responsible for promoting consistency across the CRA. Strategic planning, well-supported submissions and professional representation can significantly improve changes of reaching these kinds of Settlements, and Experienced Tax Counsel can help.
For help with a CRA Audit, please click here.
For an updated Index of our Tax Audit Series, click here.
The content of this article is intended to provide a general guide to the subject matter. Specialist advice should be sought about your specific circumstances.
[View Source]