- within Strategy, Intellectual Property and Criminal Law topic(s)
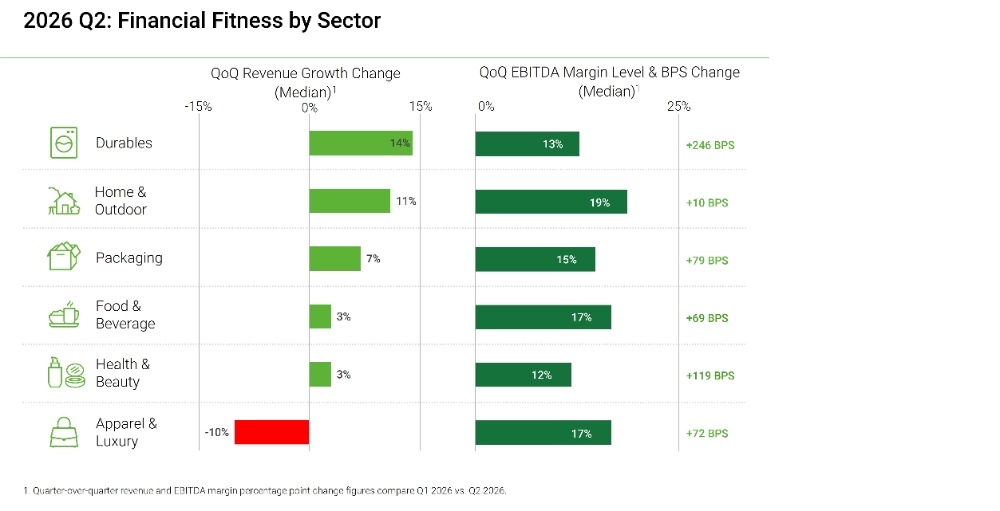
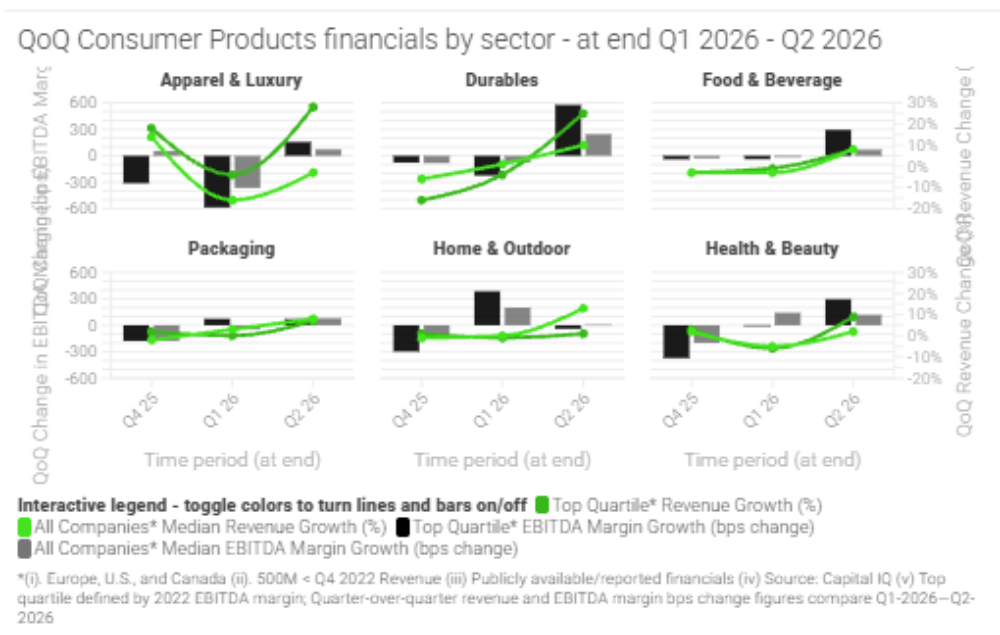
In Q2 2026, median performance diverged sharply across consumer subsectors versus Q1, with Home & Outdoor staging the strongest reversal — median revenue growth swung from -4% to +11% and margins expanded 10 bps, reflecting a warm-weather outdoor season.
Durables followed a similar pattern with 14% median revenue growth and 246 bps of EBITDA expansion, the largest margin gain of any sector, consistent with the tariff-refund tailwind flowing through to consumers for big-ticket categories.
While Food & Beverage, Health & Beauty, and Packaging held steady, Apparel & Luxury remained the clear laggard on the top line at -10% median revenue growth, despite 72 bps of margin expansion. The FIFA World Cup lift accrued disproportionately to top-quartile sportswear names rather than the median apparel operator, who continued to face price fatigue and value-conscious consumer behavior.
The Q2 median story was about the sectors that caught a specific tailwind; the question for Q3 is what happens next with the administration contemplating fresh tariffs against Canada, while the ongoing Iran war keeps oil prices at elevated levels.
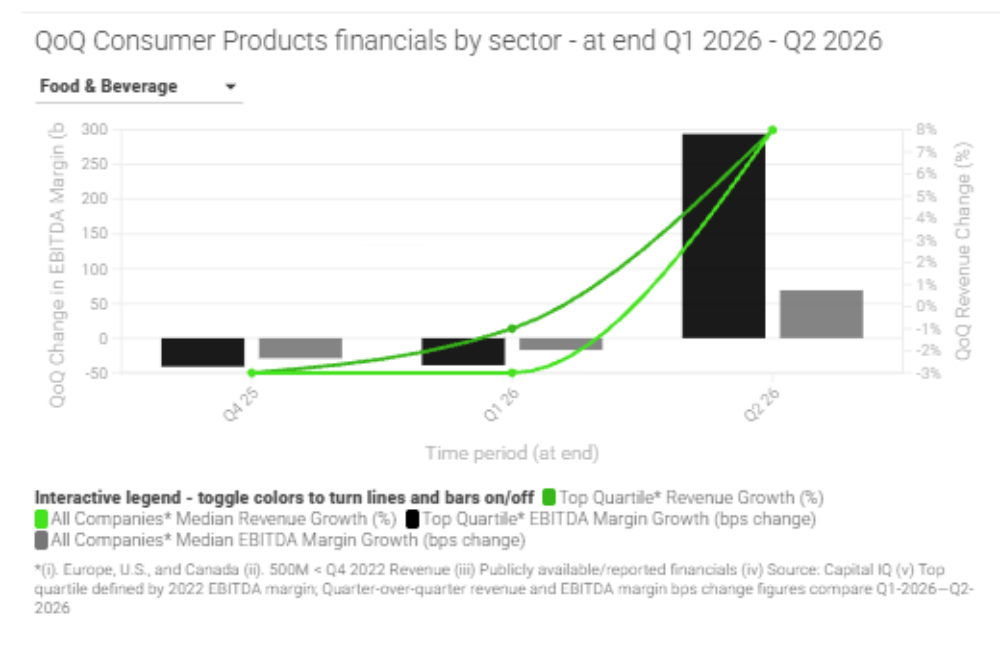
On a monthly basis, AlixPartners charts sales, sentiment and supply chains in consumer-facing businesses. Learn more about the Consumer Products Corner newsletter and read previous articles, here.
The content of this article is intended to provide a general guide to the subject matter. Specialist advice should be sought about your specific circumstances.
[View Source]