
The second update this year reveals changes in the audit process and associated procedures.
ICE has quietly updated its Form I-9 inspection guidance for the second time this year. The August 31, 2026 update to the Form I-9 Inspection Under Immigration and Nationality Act § 274A Fact Sheet does not change the substantive and technical violation framework announced earlier this year, but it offers useful insight into how ICE intends to conduct audits and assess employer compliance.
The most notable change is a new Notice of Expired or Rescinded Immigration Status and/or Employment Authorization, which may be issued when an employee loses work authorization after an audit begins. ICE states that this notice does not, by itself, allege employer wrongdoing, but it signals the agency’s continued focus on work authorization issues that arise during audits.
ICE also clarified its penalty methodology, confirming that violation percentages are calculated separately for paperwork violations and uncorrected technical errors, on the one hand, and knowingly hiring or continuing to employ unauthorized workers, on the other. This clarification appears to address concerns that paperwork deficiencies and unauthorized-worker violations could effectively be counted twice, creating a “double penalty” scenario in determining the applicable penalty range. Employer groups, bar associations, and other stakeholders have sought clarification on this issue for years, making this one of the more welcome aspects of the updated guidance.
Although the August 2026 update does not change the violation categories announced earlier this year, employers should not view it in isolation. The procedural changes build on a significantly stricter enforcement framework that reclassified a number of commonly encountered Form I-9 deficiencies from technical to substantive violations. These changes affect a broad range of errors, including missing dates of birth, missing A-numbers or USCIS numbers where required, missing employee signature dates, incomplete preparer/translator information, incomplete Section 2 document information, missing first-day-of-employment information, improper use of remote verification procedures, and deficiencies in electronic Form I-9 audit trails and system documentation. As a result, errors that historically could be corrected without penalty may now result in substantive violations and immediate fines, making proactive audits, timely corrections, and effective electronic Form I-9 compliance programs more important than ever.
The revised guidance also highlights ICE’s continued focus on electronic Form I-9 systems. Employers should confirm their systems can produce legible Forms I-9, maintain compliant audit trails, and generate supporting records required during an inspection. Recent inspections also suggest increased scrutiny of older or legacy electronic Form I-9 systems, with auditors asking more detailed questions regarding audit trails, historical corrections, indexing capabilities, and system architecture. While not a routine audit request, in one recent inspection ICE requested a live demonstration of the employer’s electronic Form I-9 system. The demonstration was intended to help establish that the system’s functionality and audit trail complied with regulatory requirements after questions were raised about the system’s operation.
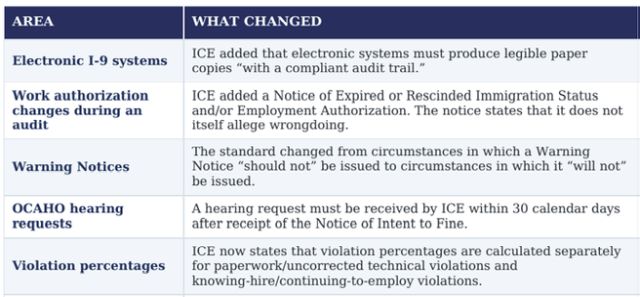
Procedurally, the Fact Sheet now states that requests for OCAHO hearings must be received by ICE within 30 days of a Notice of Intent to Fine, rather than merely “made” within that period. ICE also directed that fines are to be issued in certain situations instead of warning notices.
Bottom Line: While the August 2026 update does not alter the substantive violation framework announced earlier this year, it provides important insight into how ICE intends to conduct audits, calculate penalties, address work authorization issues discovered during inspections, and evaluate electronic Form I-9 systems. Employers should use this update as an opportunity to review their Forms I-9, electronic compliance systems, audit-response procedures, and overall compliance strategy before an inspection occurs. Proactive compliance efforts, particularly audits conducted with experienced immigration compliance counsel and under attorney-client privilege where appropriate, can help employers identify and address issues before they become the subject of a government inspection.
The content of this article is intended to provide a general guide to the subject matter. Specialist advice should be sought about your specific circumstances.
[View Source]
