Canadian businesses that buy services or intangible property from suppliers outside Canada often assume that if the foreign supplier does not charge GST/HST, none is owed.
Section 218 of the Excise Tax Act says otherwise. It requires the Canadian recipient, not the foreign supplier, to calculate and remit the GST directly to the CRA.
Businesses that overlook this obligation, most commonly those with exempt or non-commercial activities such as financial services, holding companies, and non-profits, can face years of accumulated unremitted tax, penalties, and interest once the CRA identifies the gap on a CRA tax audit.
Any Canadian business that pays for consulting, licensing, software, marketing, or professional services from a non-resident supplier should understand when section 218 applies and how to comply with it.
This article explains the imported taxable supply rules under Division IV of Part IX of the Excise Tax Act, walks through when self-assessment is required, and sets out the practical steps a business should take to avoid an unpleasant surprise on its next CRA tax audit.
Background: How the Excise Tax Act Taxes Imports of Services and Intangibles
The GST/HST is not a single tax collected in a single way. Part IX of the Excise Tax Act splits taxation into separate divisions depending on the nature of the transaction.
Division II taxes domestic supplies made in Canada, where the supplier collects the tax from the recipient.
Division III taxes imported goods, where the Canada Border Services Agency collects the tax at the border. Neither of these divisions works for a service performed outside Canada or intangible personal property, such as a software licence or royalty right, supplied by a non-resident with no physical goods crossing the border and no obligation on the non-resident to register for or collect GST/HST.
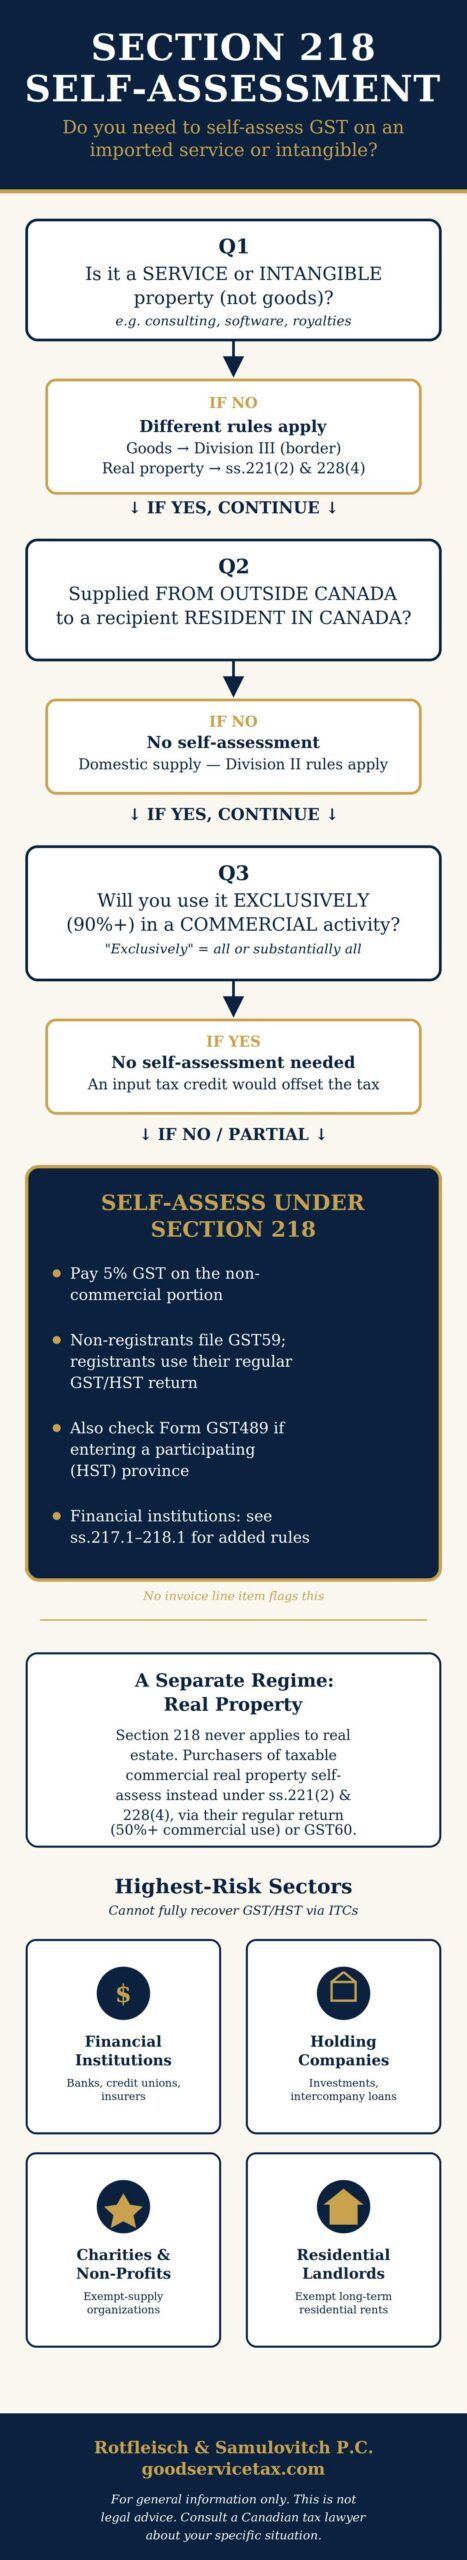
Division IV closes this gap. Section 217 defines an “imported taxable supply” as, broadly, a supply of personal property (other than goods) or a service made outside Canada to a Canadian resident recipient, where the recipient will use the supply otherwise than exclusively in a commercial activity. Section 218 then imposes the tax: the recipient of an imported taxable supply must pay GST calculated at the current rate of 5 percent on the value of the consideration for that supply. Because the foreign supplier has no collection obligation, the CRA relies on the Canadian recipient to self-report and remit.
The self-assessment obligation is reported using Form GST59, GST/HST Return for Imported Taxable Supplies and Qualifying Consideration, for non-registrants, or through the recipient’s regular GST/HST return where the recipient is already registered.
Which category a business falls into can turn on issues discussed in our article on retroactive GST/HST registration, particularly for businesses that discover a registration gap at the same time as a section 218 exposure.
Businesses that also bring goods, services, or intangible property into a participating (HST) province may face an additional layer of self-assessment for the provincial portion of the HST under a related set of provisions, reported on Form GST489.
The rule exists because Canada’s commercial activity test already protects registrants who use a purchased service or intangible entirely in their commercial activity. A fully taxable business that imports a consulting service for use in its commercial activity generally does not self-assess under section 218, because it would simply claim an offsetting input tax credit if the supply had been taxed domestically.
Section 218 targets the cases where that offset does not exist: financial institutions, holding companies, charities, non-profits, and businesses making exempt supplies, all of which cannot fully recover GST/HST through input tax credits and therefore have an incentive, intentional or not, to source services from abroad.
Key Issues and Findings: When Self-Assessment Applies and When It Does Not
Three conditions must generally be met before section 218 applies to a particular purchase.
First, the supply must be a service or intangible personal property, not tangible goods. Imported goods are taxed separately under Division III at the border, so section 218 does not duplicate that tax.
Second, the supply must be made outside Canada to a recipient resident in Canada. Place-of-supply rules under the Excise Tax Act determine where a service or intangible is considered to have been supplied, and this determination is not always intuitive, particularly for services delivered remotely or intangible property with no clear physical location.
Third, and most significant in practice, the recipient must not be acquiring the supply exclusively for use in a commercial activity. “Exclusively” has been interpreted by the CRA to mean all or substantially all, generally 90 percent or more. A business that is a fully taxable registrant and uses an imported service entirely in its commercial activity falls outside section 218. A business that makes even a modest proportion of exempt supplies, such as a mixed lender making both commercial and exempt financial supplies, may be required to self-assess on the portion of the imported supply attributable to non-commercial use.
The definition of imported taxable supply also carves out specific exclusions: supplies already subject to tax under Division II or III, zero-rated supplies, property described in Schedule VII to the Act, and prescribed supplies.
For a fuller discussion of how zero-rated and exempt supplies are classified under the Excise Tax Act, see our guide to GST/HST zero-rated and exempt supplies.
Financial institutions are subject to a further, more detailed self-assessment regime under sections 217.1, 217.2, 218.01, and 218.1, which was introduced to address qualifying consideration among related entities and is beyond the scope of the general rule discussed here.
The tax is calculated on the value of the consideration for the supply, which usually means the invoiced price paid to the non-resident supplier. Where the supply is used partly in a commercial activity, only the non-commercial portion is subject to self-assessment.
Getting this apportionment wrong, or missing the requirement altogether, is one of the more common exposures the firm sees surface during a CRA tax audit of a financial services business, holding company, or non-profit organization.
Self-Assessment in the Real Estate Context: A Related but Separate Regime
Section 218 self-assessment is sometimes confused with a different, and more commonly encountered, self-assessment obligation that applies to real property. The two should not be conflated. Section 217 defines “personal property” as property other than real property, so real estate transactions fall outside section 218 entirely regardless of who the purchaser is or how the property will be used.
Real property has its own self-assessment mechanism under subsection 221(2) and subsection 228(4) of the Excise Tax Act. On a taxable sale of commercial real property, the vendor is generally relieved of the obligation to collect GST/HST where the purchaser is a GST/HST registrant and is not an individual acquiring a residential complex.
In that situation, the purchaser, not the vendor, must self-assess and remit the tax directly. A purchaser who will use the property primarily, meaning more than 50 percent, in commercial activities reports the self-assessed tax on their regular GST/HST return for the reporting period in which the tax became payable.
A purchaser who does not meet that threshold instead files Form GST60, GST/HST Return for Acquisition of Real Property, and remits by the end of the month following the month in which the tax became payable. This mechanism exists to spare purchasers the cash-flow burden of paying GST/HST upfront on a high-value transaction and then waiting to recover it through an input tax credit.
A related concept, the self-supply rules, applies to builders and developers of residential real property rather than to purchasers, and is triggered on substantial completion of construction or substantial renovation rather than on a sale. Our article on the self-supply rules for residential real estate developers discusses that regime in detail. The common thread across all three regimes, section 218 for imported services and intangibles, subsection 228(4) for purchased real property, and the self-supply rules for developers, is that the CRA is shifting the compliance burden onto the party best positioned to know the facts, rather than relying on the more usual vendor-collects model.
Implications for Canadian Taxpayers
Section 218 exposure is easy to miss because there is no invoice line item prompting the business to act. The non-resident supplier typically bills a clean, GST-free amount, and unless the business’s finance team specifically screens accounts payable for imported services and intangibles, the obligation can go unnoticed for years.
The financial exposure compounds over time. Because self-assessment is a recipient obligation rather than a collection obligation, the CRA can reassess the recipient directly for GST it never charged anyone, plus interest, going back to the normal reassessment period and, where the CRA alleges a misrepresentation attributable to neglect, carelessness, or wilful default, beyond it.
A gross negligence penalty of 25 percent under section 285 of the Excise Tax Act can also apply where the CRA takes the position that a missed self-assessment was more than an innocent oversight, as discussed in our guide to GST/HST gross negligence penalties, though the CRA carries the burden of proving that position on a balance of probabilities.
Businesses at the highest risk share a common feature: they cannot fully recover GST/HST through input tax credits. This includes banks, credit unions, insurers, and other financial institutions, whose exempt financial services are discussed in our case commentary on the financial services exemption; holding companies that hold investments or intercompany loans rather than carrying on a commercial activity; charities and non-profit organizations; and residential landlords whose rental income is exempt. Any of these businesses that pay a foreign parent, affiliate, or third party for management fees, licensing, marketing, consulting, or software as a service should specifically review those payments for section 218 exposure.
Takeaway
Section 218 shifts the compliance burden for imported services and intangible property onto the Canadian recipient, and it targets precisely the businesses least equipped to notice it: those making exempt or non-commercial supplies who receive no input tax credit to flag the transaction. A periodic review of accounts payable for cross-border service and licensing payments, paired with a clear apportionment methodology for mixed-use purchases, is the most reliable way to catch exposure before the CRA does.
“Section 218 catches businesses that have never missed a GST/HST return in their lives, because the obligation never shows up on an invoice. If your business makes exempt supplies and pays a foreign supplier for services or software, assume the CRA will ask about it on your next audit, not whether it will.”
— David J. Rotfleisch, Certified Specialist in Taxation Law (Law Society of Ontario).
Pro Tax Tips
Businesses that make any exempt or non-commercial supplies should build a standing accounts payable review that flags any invoice from a non-resident supplier for services, software, licensing, royalties, or consulting, since these are the payments most likely to trigger a section 218 obligation. Where a business has both commercial and exempt activities, it should document the methodology used to apportion imported supplies between commercial and non-commercial use, because the CRA will expect a reasonable and consistently applied basis for that split on a CRA tax audit rather than an after-the-fact estimate.
A business that discovers a historical failure to self-assess under section 218 should consider a voluntary disclosure before the CRA identifies the gap independently, since a complete and voluntary correction made before contact from the CRA can avoid the gross negligence penalty and, in appropriate cases, obtain partial interest relief, as discussed in our Voluntary Disclosures Program guide. Given the complexity of the place-of-supply rules and the “exclusively commercial” threshold, a business with significant cross-border service or intangible purchases should have an experienced Canadian tax lawyer review its exposure before, rather than after, an audit begins.
Frequently Asked Questions
What is an imported taxable supply under the Excise Tax Act?
It is generally a supply of a service or intangible personal property made outside Canada to a recipient resident in Canada, where the recipient will not use the supply exclusively in a commercial activity. Supplies of goods, zero-rated supplies, and certain other categories are excluded from the definition.
Does section 218 apply to imported goods?
No. Imported goods are taxed separately under Division III of the Excise Tax Act, generally collected by the Canada Border Services Agency at the time of importation. Section 218 applies only to services and intangible personal property.
Who has to self-assess GST under section 218?
The Canadian recipient of the imported taxable supply, not the non-resident supplier. The non-resident generally has no obligation to register for or collect GST/HST on these supplies.
What does “exclusively in a commercial activity” mean?
The CRA generally interprets “exclusively” as all or substantially all, commonly understood as 90 percent or more. A business that uses an imported service entirely, or almost entirely, in its GST/HST-taxable commercial activity generally does not need to self-assess.
Which businesses are most likely to be affected?
Financial institutions, holding companies, charities, non-profit organizations, and other businesses that make exempt supplies or hold investments rather than carrying on a fully taxable commercial activity are most exposed, because they cannot fully recover GST/HST through input tax credits.
What form is used to self-assess under section 218?
A non-registrant generally uses Form GST59, GST/HST Return for Imported Taxable Supplies and Qualifying Consideration. A registrant reports the self-assessed amount through its regular GST/HST return.
Is there a separate self-assessment requirement for the provincial part of the HST?
Yes. A related set of provisions requires self-assessment of the provincial portion of the HST when property or services are brought into a participating province, reported using Form GST489 for non-registrants.
What happens if a business never self-assessed and the CRA finds out on audit?
The CRA can reassess the unremitted GST for the normal reassessment period, add arrears interest, and, where it takes the position that the omission resulted from neglect, carelessness, or wilful default, reassess beyond the normal period and apply a gross negligence penalty equal to 25 percent of the unremitted tax under section 285 of the Excise Tax Act.
Can a business fix a missed section 218 obligation before the CRA catches it?
Yes. As explained in our taxpayer’s guide to the Voluntary Disclosures Program, a voluntary disclosure made before the CRA has taken any enforcement action against the business can allow it to correct the omission, pay the underlying tax and interest, and in many cases avoid the gross negligence penalty.
Do financial institutions have different self-assessment rules?
Yes. Financial institutions are subject to additional, more detailed import rules under sections 217.1, 217.2, 218.01, and 218.1 of the Excise Tax Act, dealing with qualifying consideration among related entities, which go beyond the general section 218 rule discussed in this article.
Does section 218 apply to software subscriptions and SaaS purchased from a foreign vendor?
It can. Software and other intangible property licensed from a non-resident supplier can fall within the definition of imported taxable supply if the Canadian recipient does not use it exclusively in a commercial activity, so the same apportionment analysis applies.
Should a business apportion the tax if an imported service is used partly for commercial and partly for exempt purposes?
Yes. Where an imported taxable supply is used partly in a commercial activity, only the portion attributable to non-commercial use is subject to self-assessment, provided the business can support the apportionment on a reasonable and consistent basis.
Does section 218 apply to purchases of real estate?
No. Section 217 defines the personal property covered by section 218 as property other than real property, so real estate transactions are governed instead by the separate self-assessment rules in subsection 221(2) and subsection 228(4) of the Excise Tax Act, which apply to the purchaser of taxable real property rather than the recipient of an imported service or intangible.
The content of this article is intended to provide a general guide to the subject matter. Specialist advice should be sought about your specific circumstances.
[View Source]