
Control capital for growth. Where venture ends and buyouts begin.
On Friday the interest rate on a 10-year US government bond hit 5.23 percent, its highest since 2007. That number sets the price of almost every deal. This week: why money costs more, what the latest software numbers say, and what the Buy, Sell or Wait panel told us. Next week: Joe Baratta is leaving Blackstone, and what generational change at funds, large and small, means for the companies they back.
Why Money Costs More
The rate the Fed sets gets the headlines. For deals, the rate that matters more is the 10-year Treasury yield, what the government pays to borrow for ten years. The 30-year rate hit 5.49 percent on Friday, its highest since 2004.
Four forces are pushing the same way at once:
- War. The conflict with Iran has driven up oil. In August, energy prices were up 16 percent from a year earlier and gasoline 27 percent, which pushed overall inflation to 3.4 percent.
- AI building. Gartner estimates data center spending at $1.37 trillion this year. Much of it is borrowed. SoftBank alone sold more than $11 billion of bonds this month to fund OpenAI. More borrowers chasing the same dollars push rates up.
- Tariffs. The St. Louis Fed estimated that tariffs added about half a point to inflation by the end of 2025.
- Fewer workers. Net immigration slowed sharply in 2025 and may have turned negative. Fewer workers means less room to grow without raising prices. So far wages have not jumped; many companies have automated instead.
Underneath all four is the federal deficit, about $2 trillion this year, with interest on the debt now about $1 trillion a year. The government has to borrow more, and lenders want to be paid more to lend it.
Economists argue about how much each matters. One number helps: inflation without food and energy was 2.4 percent in August. Much of the jump is oil, and some of it would ease if the war ends. The rest would not. Deficits, AI building, tariffs and a smaller workforce do not go away with a ceasefire. Plan for rates to stay high, not to come down. Markets see about a two-in-three chance the Fed raises rates again on October 27 and 28.
The Loan Desk
The price of money is up. The price of risk is not. The extra interest investors demand on high-yield company bonds, above what the government pays, was 2.8 percentage points last week, below its ten-year average. Lenders are still willing to lend. What changed is the base rate underneath the loan.
Two rates matter for a buyout, and they do different jobs. The short-term rate, which follows the Fed, sets what the buyer pays on its loan each quarter. The long-term rate sets what the company will be worth when the buyer sells it in a few years. Both are up, so buyers are paying more to borrow and expecting less on the way out. That is why they offer less today.
Software: Two Markets
Jefferies’ latest monthly numbers, with thanks again to Rob Bartlett, show public software splitting in two.
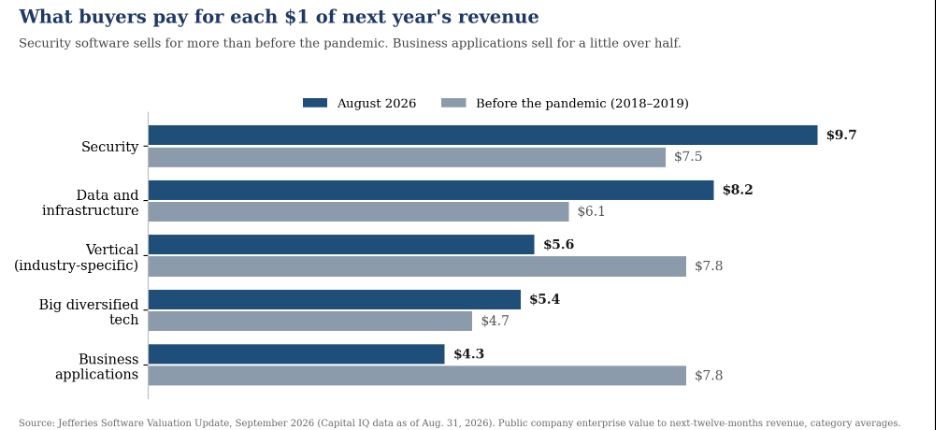
Security software sells for $9.70 for each dollar of next year’s revenue, more than before the pandemic. Business applications, the software a company buys per employee, sell for $4.30, a little over half their old price. Over the past year security stocks rose 66 percent and business application stocks fell 21 percent.
Beating forecasts is no longer enough. Last quarter 87 percent of public software companies beat revenue forecasts, yet only 48 percent of their stocks went up afterward.
Rates explain part of it. When a government bond pays 5 percent, a dollar of profit promised five years from now is worth less today. Growth still earns a premium, but a smaller one. In November 2021, investors valued a point of revenue growth about five times as much as a point of cash margin. Today it is under two times.
Buy, Sell or Wait: What the Panel Said
Thank you again to Jason Babcoke of Sumeru, Rob Bartlett of Jefferies, Harish Belur of Riverwood and Gargi Ray of Synopsys. The full write-up is here. The short version:
- Twenty percent is the line. Software companies growing faster than about 20 percent a year sell for roughly twice the price of slower ones, public or private. Miro, valued at $17.5 billion in 2022 with about $600 million of annual recurring revenue, just sold to Bending Spoons for about $1.36 billion.
- AI is eating headcount before it eats software. Customers treat AI spending and payroll as one budget: headcount flat, AI spending up. Installed software is not being ripped out, but sales take longer. One panelist said this is 1995, not 1999. Early, not the top.
- Buyers diligence the future. Past retention numbers are no longer enough. Buyers want the roadmap, the engineers, whether win rates are rising, and whether the product matters more or less as AI models improve. They will ask who owns code written with AI tools and whether customer contracts allow training on customer data. Those are cheap fixes a year out and expensive ones mid-deal.
- You are in a process from the first investor meeting. A sale takes about a year: six months to prepare, six to run. Buyers care about their own return (for a sponsor, typically three times the money in five years) or their product gap (for a strategic buyer), not what you were worth in 2021.
- Growth still beats margin. The cost cutting of 2023 and 2024 was not rewarded as much as hoped. A company that cannot fund four quarters of growth on its own should raise money, not sell.
- Keep the structure simple. Investors prefer a realistic price and plain common stock to complicated protections. Earnouts need one revenue line and a clear measuring period. AI and cyber risks the deal insurance excludes come back to the seller.
The room’s conclusion: waiting is a legitimate strategy. Drifting is not.
The Growth Tape
Technology. Cyera, a data security company, raised about $400 million at a valuation near $12 billion, the security premium above in action. Progress Software closed its roughly $400 million purchase of Domo’s AI and data business. Progress bought the assets, not the company, so Domo keeps its cash and tax history.
Life sciences. A correction to last week: the IPO market for biotech is open, for companies with clinical data. By BioSpace’s count, 20 biotech companies have gone public this year, against eight in all of 2025, and PitchBook counts more than $4 billion of crossover investment, the private round that sets up a public offering.
In the Courts
- Anderson v. Intel is argued at the Supreme Court on Tuesday, October 6. It will shape how much 401(k) money reaches private equity.
From My Desk
- Private Equity’s $285 Billion Shock Year Still Has Real Openings, on Foley Ignite.
- Where We Are on Software M&A, with data from Rob Bartlett and Jefferies.
- Missed last week? The Growth Docket, No. 2.
On the Calendar
Ready for Anything: IPOs, SPACs and Capital Market Shifts, Tuesday, October 6, Foley San Francisco, with Open Future Forum. Register.
LP/GP Event with Jersey Finance, Monday, October 12, Foley San Francisco. Reply for a seat.
Investors on the Bay, a Fall Mixer, Friday, October 23, San Francisco. Register.
One Way Ventures Summit, Wednesday, October 28, San Francisco. Register.
General Counsel Executive Forum, Private Lunch, Friday, October 30, San Francisco. In-house counsel only. Request a seat.
IPO Readiness, Wednesday, November 18, San Francisco, with SVB, Protiviti and Heffernan. Reply for a seat.
2027 Outlook, Friday, December 11. Reply for a seat.
Thank you to Chris Yeh and everyone who came to Hard Things on Monday for a sharp conversation on robotics and physical AI.
Closing Argument
- Anyone planning to borrow in 2027: build the plan on rates staying where they are. If they fall, that is a bonus.
- Software founders thinking about a sale: growth above 20 percent still roughly doubles the price. Start the cleanup a year before you need it.
- Everyone else: buy, sell or wait on purpose. Waiting is a strategy. Drifting is not.
Rates set the backdrop. Preparation sets the price. The companies that are ready get to choose.
The content of this article is intended to provide a general guide to the subject matter. Specialist advice should be sought about your specific circumstances.
[View Source]